How to Track Daily Spending Without Burning Out
You know how this goes. A fresh spreadsheet, a tidy tab for every category, and a firm intention to log every purchase. Eleven days later the file is open but empty, and the thought of catching up on a week of receipts feels like homework. The problem was never your discipline. The problem was the method.
Tracking daily spending works when it costs almost nothing: under a minute a day, with no decisions to make. Here is a version that survives a busy Tuesday.
Why detailed tracking collapses
Most spending logs die from decision fatigue. Every entry demands a judgement. Was that a grocery shop or a household shop? Do you split the receipt? Is a birthday card "gifts" or "miscellaneous"? If you have ever argued with yourself about whether coffee counts as "treats" or "food", you have found the flaw.
Multiply that by four transactions a day and the log becomes a small part-time job. The fix isn't a better spreadsheet. It's deleting the decisions.
The one-minute method
One entry per day. Not per purchase. You record three things: the date, the rough total that left your account, and one word for what dominated the day.
- Anchor it to something you already do. The moment you sit down with a cup of tea after work, or the last thing you do before you plug your phone in to charge.
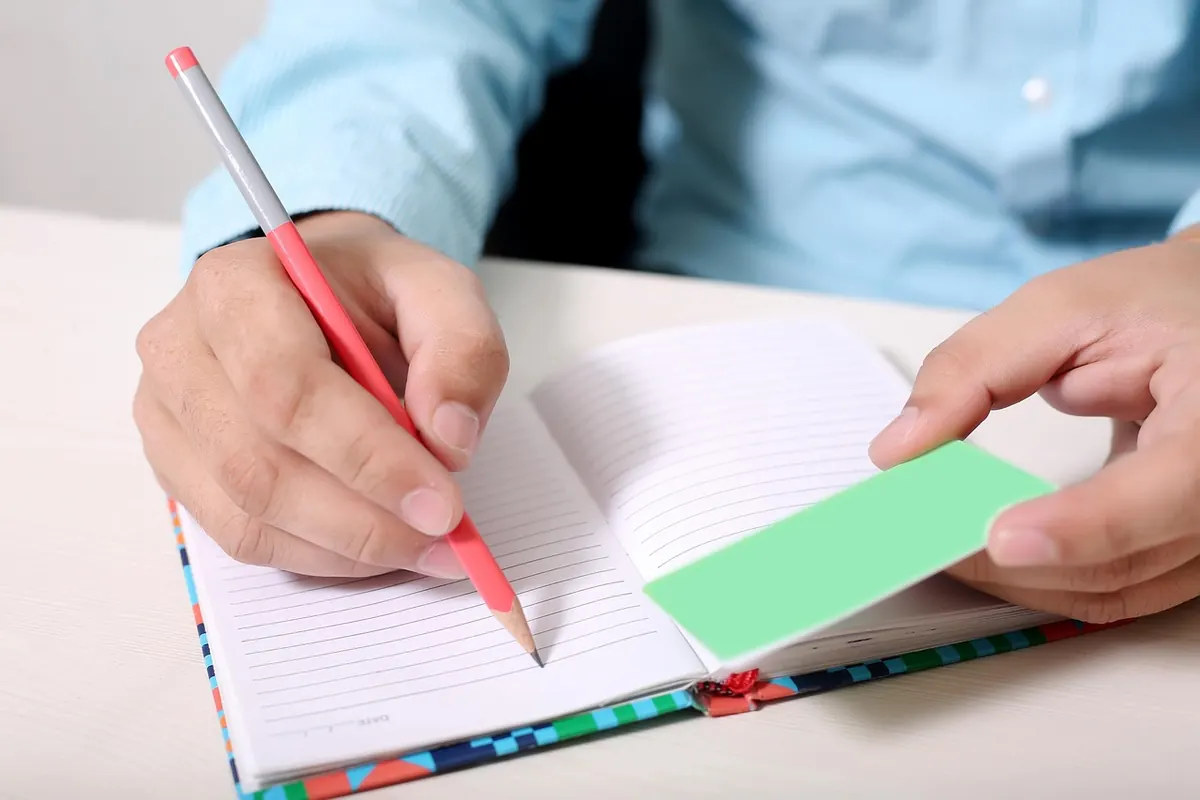
- Use something already open. A notes app, a small notebook, the back page of a diary. One page, no tabs, no dropdowns.
- Write the date, a total and a word. 12th — £43 — supermarket. Round to the nearest pound if that's easier. The figure doesn't have to be exact to be useful.
- Close it. Don't total the week, don't judge the number, don't tidy the entries into columns.
To find the total, check your banking app and add up what left the account. If something hasn't appeared yet — a small contactless tap, a pending card payment — estimate it and move on. An approximate figure written down beats an exact one you never get round to writing.
What if you've forgotten what you spent?
Write what you remember and add a question mark. Wednesday — £20? — lunch out. A slightly wrong line in a notebook will not mislead you in any meaningful way. A blank week will.
What is genuinely worth recording
The daily total is the spine of the log. Beyond that, be ruthless about what earns a place.
Worth noting:
- Any single purchase big enough to distort the day — a train ticket, a new tyre, a wedding present.
- Anything that felt like a decision rather than a habit. That is where your money actually moves.
- One-offs you would otherwise forget when the month looks strange: the boiler repair, the school trip payment.
- The days you spent nothing. Those entries are quietly encouraging.
Not worth noting:
- Every individual coffee, snack and bus fare. The day's total covers them.
- Supermarket receipts split into nine categories. Nobody has ever enjoyed this.
- Standing orders and direct debits. They arrive once a month and rarely change.
- Which shop, which card, which app. Irrelevant at this level.
If you want category detail, your bank statement already holds it, and it will still be there in three months whether you look at it or not.
The single word matters more than the number
That one word — supermarket, petrol, birthday, nothing, silly — is what turns a list of figures into a pattern. After three weeks, reading down the column tells you something a statement never will: which days are expensive, and what sets them off.
You don't need twelve categories to spot that Fridays are costly. You need the word "Friday" sitting next to a number that is consistently larger than the others. Keep the vocabulary small, too. Ten repeated words beat forty precise ones, because you will actually use them.
Review weekly, not daily
The daily entry takes under a minute. The thinking happens once a week, in about ten minutes, and it comes down to three questions:
- Which day cost the most?
- Why?
- Is anything repeating?
Write the answers in one sentence each. That's the whole review. Don't recategorise anything — the log is a record, not a filing system.
Once a month, add up the daily totals and compare that figure with what came in. If the month's spending sits comfortably below your income, you don't need to change a thing. If it doesn't, you now have a list of specific days to examine rather than a vague sense of worry.
When you miss days
You will miss days. That is not failure; it is the ordinary texture of a busy life. Two habits stop a gap from ending the whole thing.
First, backfill roughly. A dash or an estimate is better than nothing, because it keeps the record visibly continuous. Second, never restart. Opening a fresh log resets everything you have learned. If January is patchy, February continues in the same notebook. A log with holes in it is still a log.
Pick a tool you would open anyway
Paper, a notes app, a plain spreadsheet — all fine. The best option is the one already open on your phone or already lying on the kitchen table.
Be cautious about leaning on your bank's automatic categorisation. It is useful for the monthly view, but because it happens without you, it builds no awareness. Automatic tracking is a record. Only you can build the habit.
Start tonight, and keep it boring
Try three days before you decide anything. Date, total, one word. Then stretch it to a week. Most people find the first useful insight arrives somewhere around day ten, when a word starts repeating.
Keep the bar low on purpose. A boring log you maintain for a year will teach you far more than an elegant one you abandon in a fortnight. And if nothing in the log has changed a single decision after a month, that is a result too: it means your spending is already steady, and you can stop worrying about it.
One caveat. If money worries are affecting your sleep, or you are behind on repayments, a notebook is not the right tool. Free, confidential help is available from services such as Citizens Advice, and asking costs nothing.
Photo: cocoparisienne / Pixabay